Juggling rotating reward categories and restrictive spending caps turns cash back tracking into an exhausting chore. You deserve an uncomplicated credit card that rewards everyday spending without demanding hours of administrative effort.
The Bank of America Unlimited Cash Rewards credit card simplifies household budgeting with a flat earnings structure. It pays an unlimited 1.5% cash back across every eligible purchase you make.
When you pair this card with qualifying banking balances, your cash return expands significantly. Here are nine compelling reasons to evaluate this card for your household wallet.
The Bottom Line Up Front
Finding the right everyday cash back card comes down to net return and simplicity. This card provides several immediate advantages for disciplined spenders.
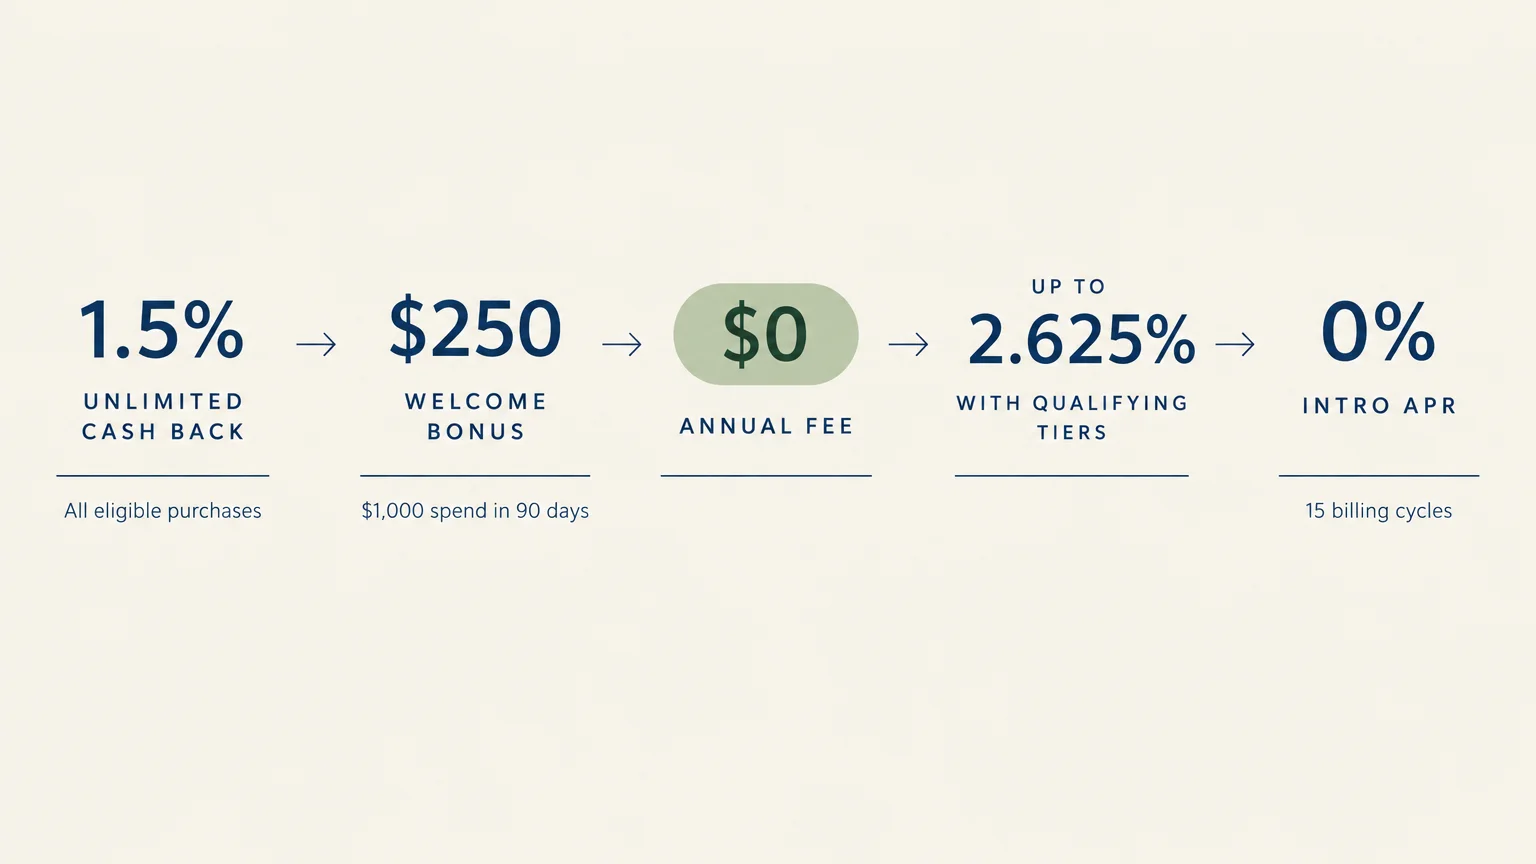
- Predictable Base Return: You earn an unlimited 1.5% cash back on all eligible purchases without category activation.
- Lucrative Welcome Offer: You can secure a $250 online cash bonus after spending $1,000 within your first 90 days.
- Zero Annual Fee: You keep 100% of your earned rewards without paying an annual membership charge.
- Tiered Multipliers: You can boost your earnings up to 2.625% through the redesigned BofA Rewards program.
- Introductory APR Relief: You receive a 0% introductory APR for 15 billing cycles on purchases and qualifying balance transfers.
1. Predictable 1.5% Flat-Rate Earnings on Every Purchase
Many rewards cards force you to track quarterly spending categories, merchant codes, and arbitrary dollar limits. That complexity often causes cardholders to miss out on the highest advertised rates.
The Bank of America Unlimited Cash Rewards card eliminates category confusion entirely. You earn a reliable, unlimited 1.5% cash back on every purchase, everywhere Visa is accepted.
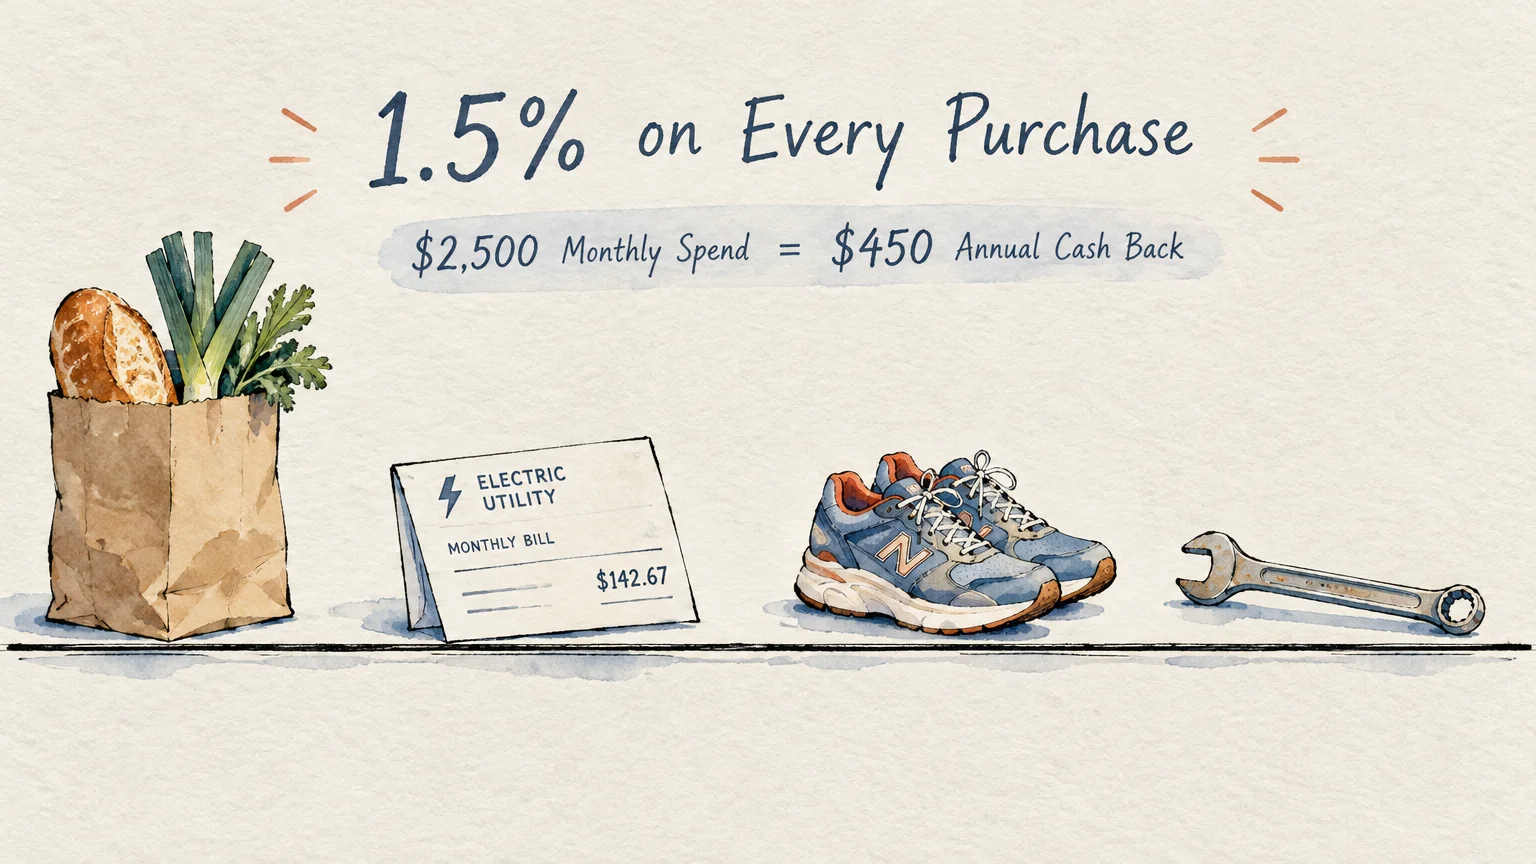
Whether you buy groceries, pay utility bills, or take your vehicle in for repairs, your earnings rate never drops. You will never have to activate a bonus category or adjust your habits around restrictive calendars.
If your household charges $2,500 each month to cover normal recurring expenses, you earn $450 in annual cash back effortlessly. That predictable cash flow lets you focus on your family budget rather than tracking complex point charts.
2. An Attainable and Generous Upfront Welcome Bonus
Credit card welcome bonuses frequently demand thousands of dollars in spending within tight timeframes. Those steep hurdles can push families into unnecessary spending just to hit an arbitrary threshold.
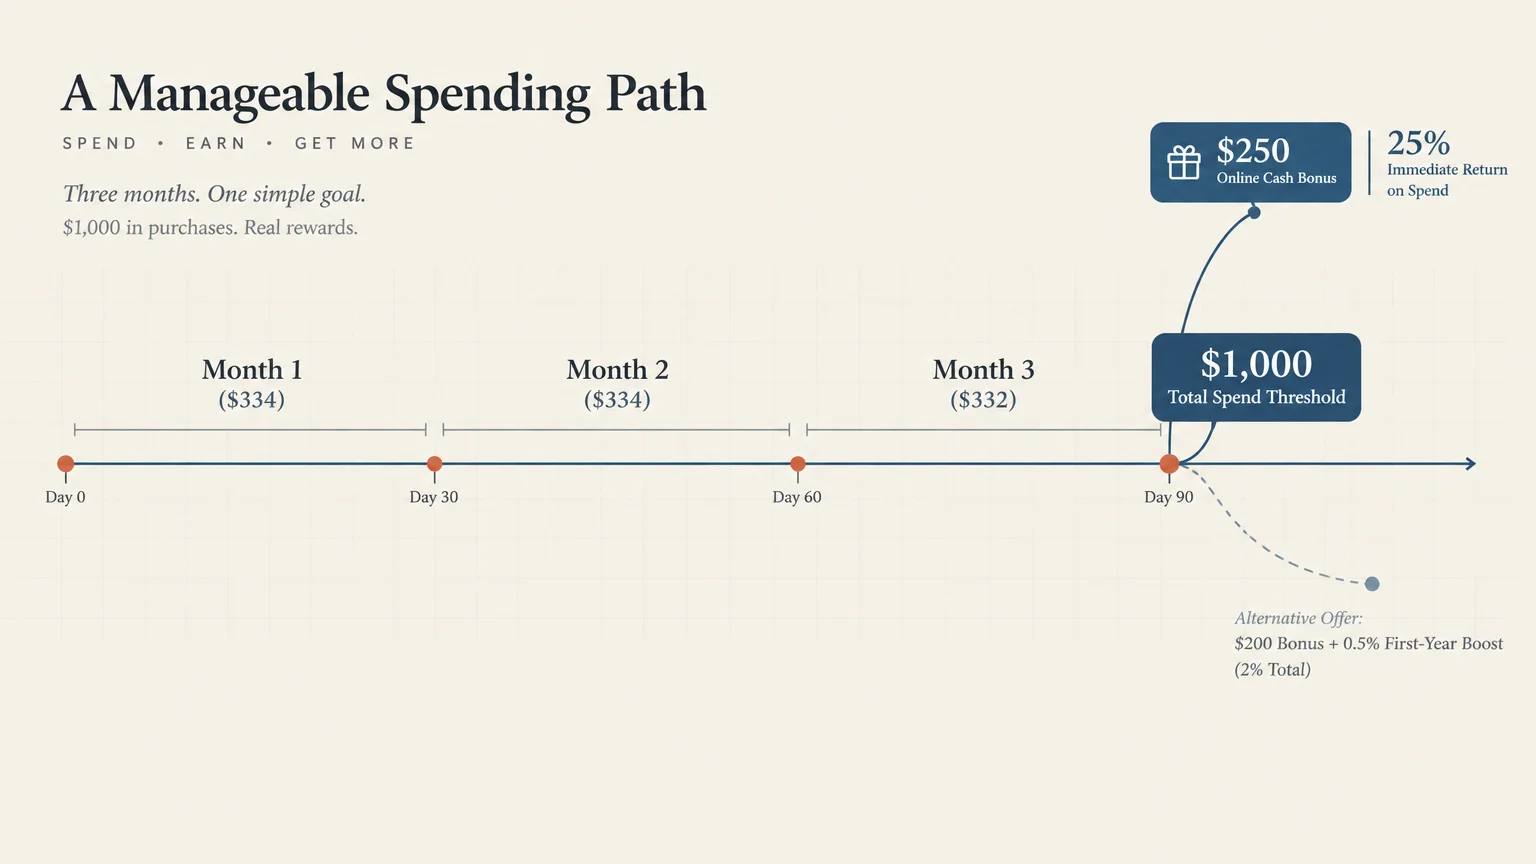
Bank of America offers a limited-time $250 online cash rewards bonus after you spend $1,000 on purchases within the first 90 days. This target requires an average spend of roughly $334 per month.
That $250 bonus represents an immediate 25% return on your initial $1,000 expenditure. Most working households can hit that requirement effortlessly by shifting standard grocery and utility payments to the new card.
Bank of America also periodically circulates an alternative welcome offer featuring a $200 bonus alongside an extra 0.5% cash back for your first year. That promotion elevates your first-year base earnings to an impressive 2% across all purchases.
3. Zero Annual Fee to Protect Your Household Bottom Line
Premium rewards cards often charge annual fees ranging from $95 to over $600. Those recurring costs force you to calculate whether your net earnings truly outpace the cost of ownership.
The Bank of America Unlimited Cash Rewards card carries a $0 annual fee. Every dollar you earn in cash back remains entirely yours to save, invest, or spend.
A $0 annual fee card also serves as an enduring foundation for your credit profile. You can keep the account open indefinitely without paying a cent, which preserves your average credit history length.
Data from the Consumer Financial Protection Bureau (CFPB) shows that maintaining long-standing accounts with clean payment histories positively supports your consumer credit profile over time.
4. Generous 0% Introductory APR on Purchases and Transfers
Financing an upcoming household purchase or consolidating existing higher-rate debt can strain any budget. High interest charges quickly consume the benefits of any rewards you earn.
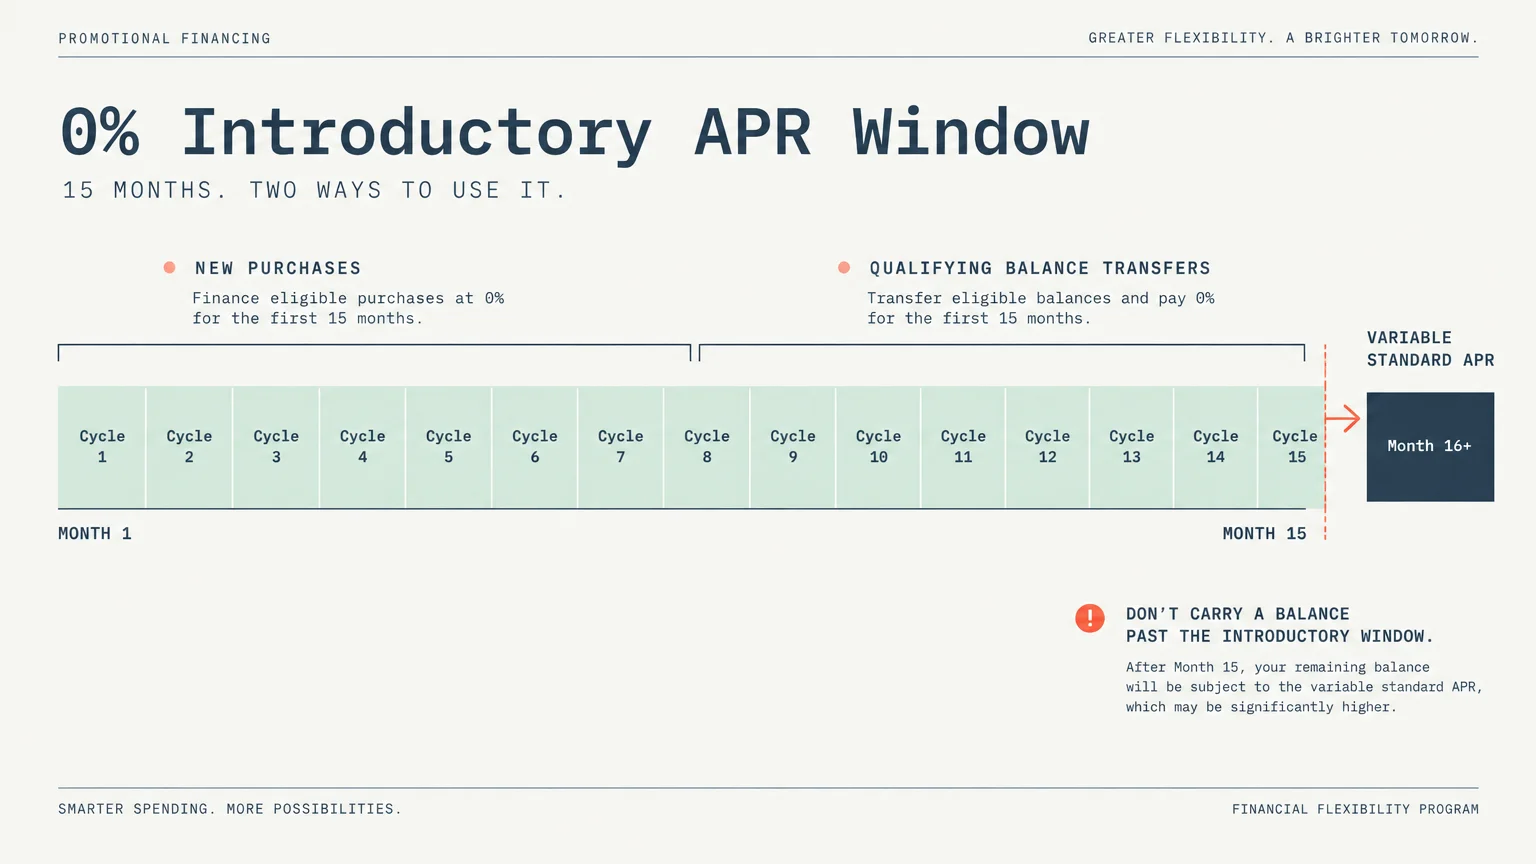
This card offers a 0% introductory APR for your first 15 billing cycles on purchases. That gives you over a year to finance essential appliances, home repairs, or medical bills interest-free.
You also receive a 0% introductory APR for 15 billing cycles on balance transfers completed within the first 60 days of account opening. A competitive 3% balance transfer fee applies during this initial 60-day window.
If you execute a balance transfer after day 60, the transaction fee increases to 5%. Planning your transfers early ensures you lock in lower upfront borrowing expenses.
Once the 15-billing-cycle introductory period ends, a regular variable APR between 17.74% and 27.74% applies based on your creditworthiness. You must eliminate your balance before this window closes to avoid interest expenses.
5. Massive Earning Multipliers Through BofA Rewards™
In late May 2026, Bank of America overhauled its loyalty framework by replacing Preferred Rewards with the upgraded BofA Rewards™ program. This transition created accessible loyalty perks for a broader group of everyday banking consumers.
Under the previous structure, members needed at least $20,000 in qualifying deposits to enter the loyalty program. Today, any consumer with an active Bank of America checking account can join the base tier with a $0 minimum balance.
BofA Rewards calculates your rewards tier using your 3-month combined average daily balance across Bank of America deposit accounts and Merrill® investment holdings. As your balance rises, your credit card rewards earn a substantial percentage boost.
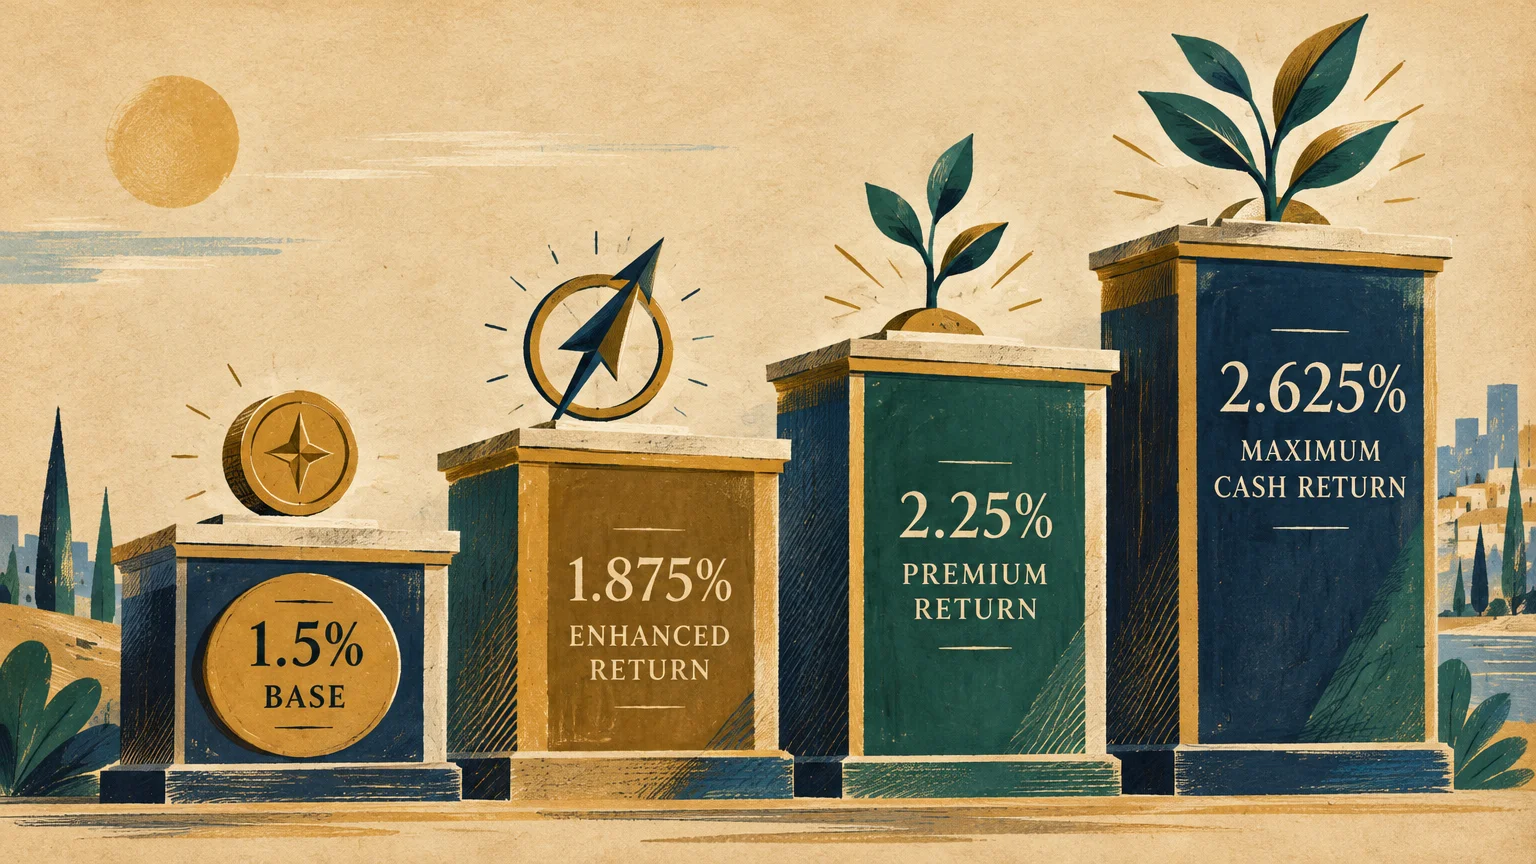
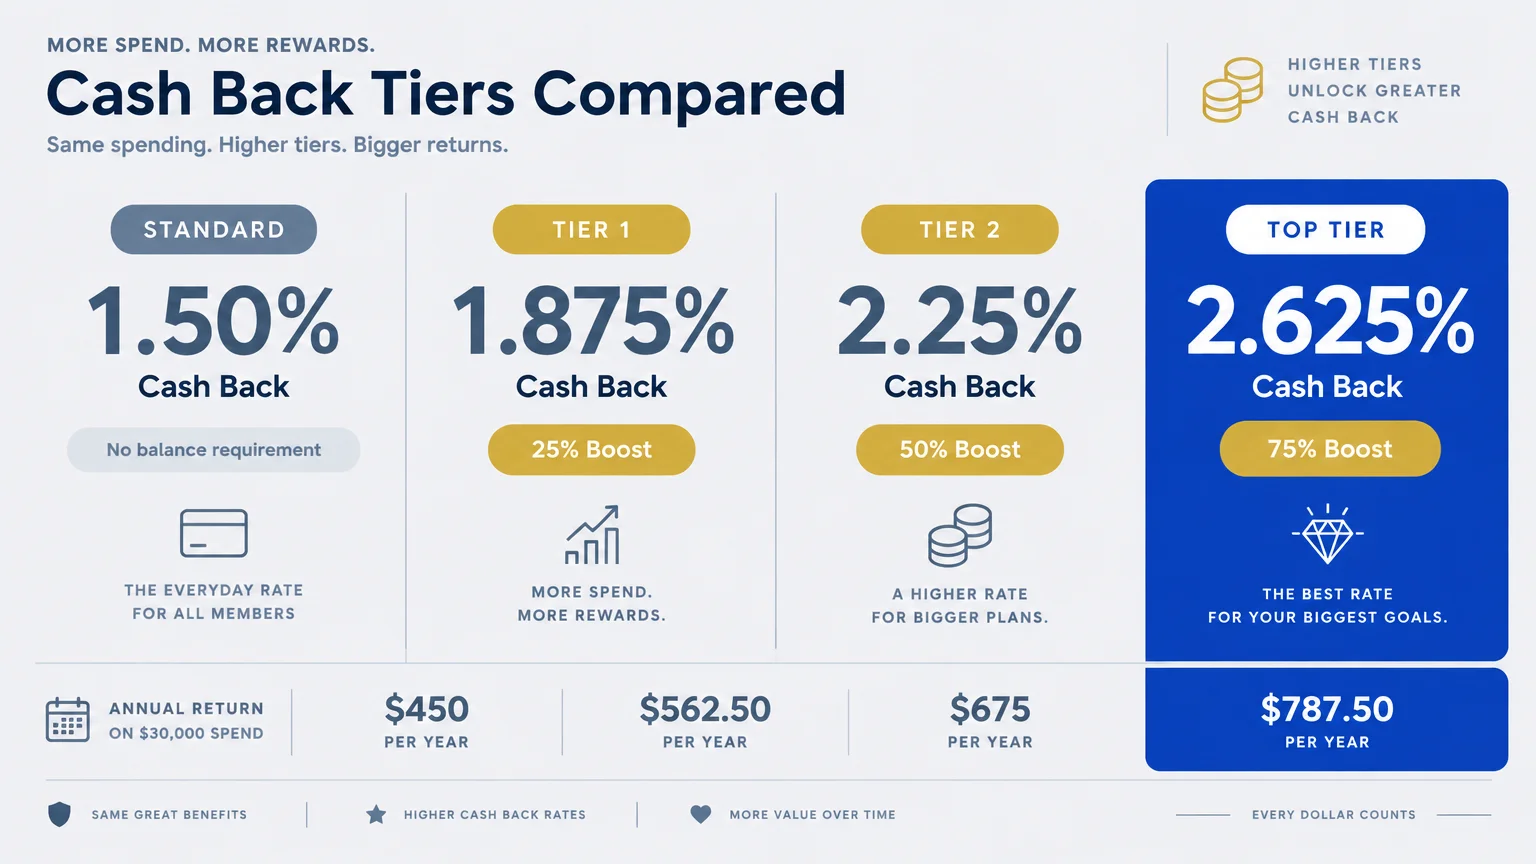
The base Member Tier ($0 to $29,999) delivers a 10% bonus, raising your effective earnings to 1.65% cash back. The Preferred Plus Tier ($30,000 to $99,999) provides a 25% bonus, elevating your return to 1.875%.
Qualifying households with $100,000 to $999,999 reach Preferred Honors, which unlocks a 50% bonus for an effective 2.25% flat cash back. Premier Tier clients with $1,000,000 or more secure a 75% boost, reaching an industry-leading 2.625% return.
“It’s not how much money you make, but how much money you keep, how hard it works for you, and how many generations you keep it for.” — Robert Kiyosaki
That boosted 2.25% or 2.625% flat earnings rate beats nearly every competing card on the market. It turns an ordinary flat-rate rewards card into an extraordinary wealth-building engine.
Evaluating the BofA Rewards Multiplier
The following table illustrates how the BofA Rewards loyalty structure enhances your earning power across various deposit levels, assuming an annual household credit spend of $24,000 ($2,000 monthly).
| Loyalty Tier | Combined Balance Requirement | Rewards Multiplier | Effective Cash Back Rate | Annual Payout ($24k Spend) |
|---|---|---|---|---|
| Standard (Non-Member) | None | 0% Bonus | 1.500% | $360.00 |
| Member Tier | $0 – $29,999 | 10% Bonus | 1.650% | $396.00 |
| Preferred Plus | $30,000 – $99,999 | 25% Bonus | 1.875% | $450.00 |
| Preferred Honors | $100,000 – $999,999 | 50% Bonus | 2.250% | $540.00 |
| Premier Tier | $1,000,000+ | 75% Bonus | 2.625% | $630.00 |
As the table highlights, placing your long-term assets with Bank of America and Merrill generates tangible cash gains. Moving from standard status to Preferred Honors delivers an extra $180 every year on identical spending.
6. Flexible Redemption Options Without Restrictive Minimums
Nothing diminishes the satisfaction of earning rewards faster than arbitrary cash-out barriers. Some institutions force you to accumulate $25 or $50 before permitting you to redeem your own money.
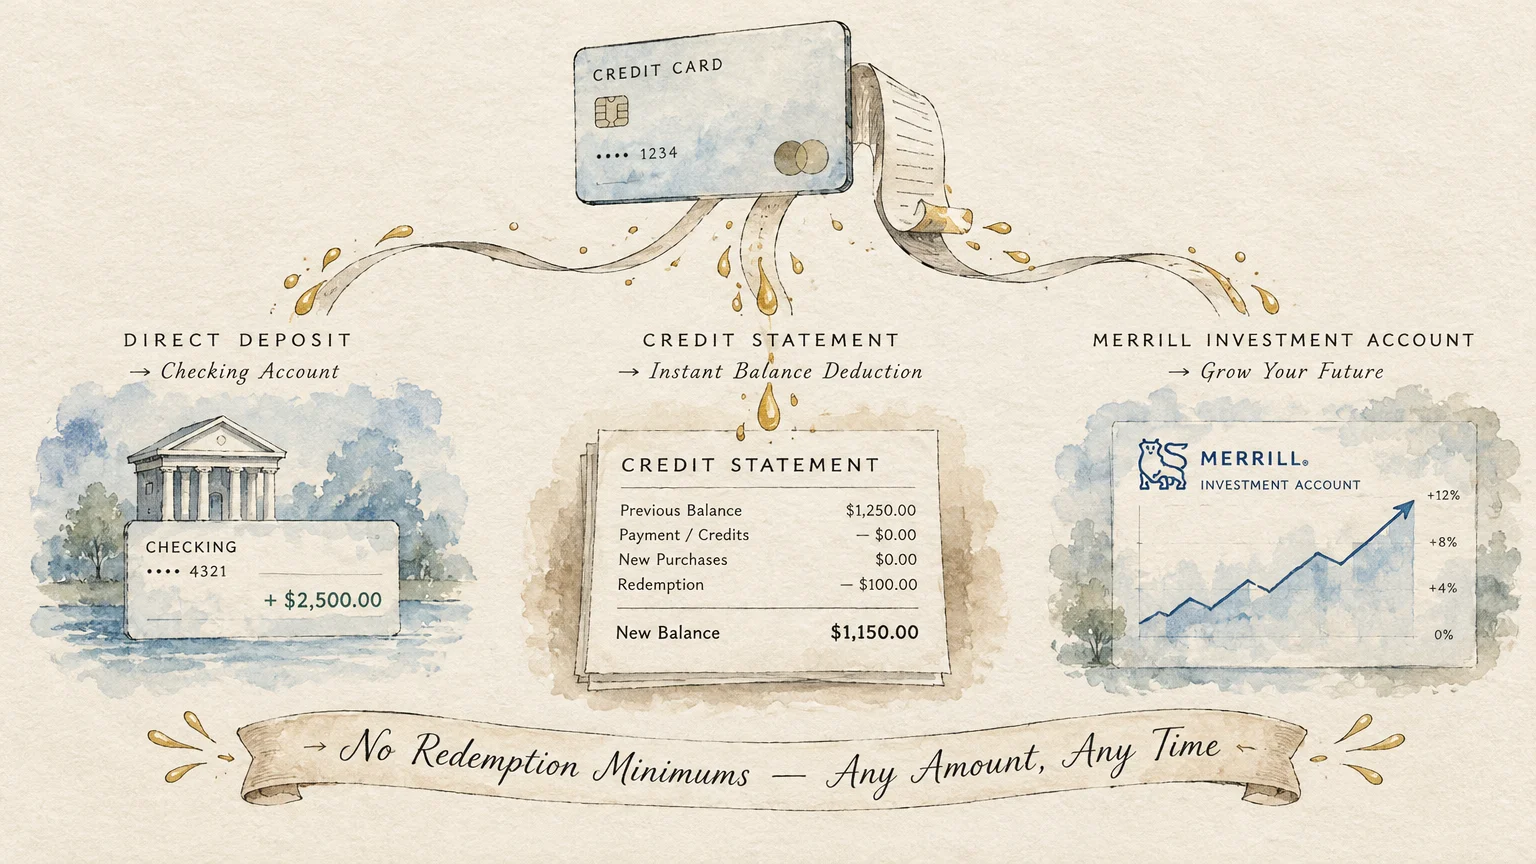
Bank of America lets you redeem your cash back in any dollar amount you choose. Whether you want to withdraw $3.15 or $315, your funds are completely accessible at any time.
You can apply your earnings as an automatic statement credit to reduce your monthly credit card balance. Alternatively, you can deposit your funds directly into an eligible Bank of America checking or savings account.
Your rewards do not expire as long as your credit card account remains open and in good standing. You can accumulate rewards for a major holiday expense or redeem them monthly to reduce everyday bills.
7. Automated Investing Potential Through Merrill Integration
Cash back is most valuable when you redirect it toward building your household wealth. Treating rewards as disposable pocket change often means those funds evaporate into minor impulse purchases.
This card allows you to direct your cash back directly into an eligible Merrill investment account. You can deposit your monthly rewards into an individual brokerage account, traditional IRA, or Roth IRA.
Redirecting an ongoing 1.5% to 2.25% cash return into diversified index funds allows your daily spending to feed your retirement goals. The compounding growth over ten or twenty years transforms routine credit spending into real financial security.
“Do not save what is left after spending, but spend what is left after saving.” — Warren Buffett
Automating your cash back redemptions directly into an investment portfolio fulfills that disciplined strategy. It ensures that every household purchase automatically funds your long-term financial independence.
8. An Accessible Student Version for Emerging Borrowers
Young adults and college students often encounter obstacles when attempting to qualify for competitive cash back credit products. Lenders frequently relegate them to secured cards that offer weak terms or zero rewards.
Bank of America provides an identical Student version of the Unlimited Cash Rewards credit card. It provides the same 1.5% flat cash back structure and $0 annual fee as the flagship consumer card.
College students can establish a positive credit history while earning cash rewards on their books, groceries, and educational supplies. Building strong habits early protects young consumers from predatory borrowing practices.
Consumers can monitor their emerging credit profiles for free using tools sanctioned by the Federal Reserve and federal regulators. Regularly checking your credit reports ensures accurate reporting as your score matures.
9. Clear Approval Rules via the Transparent 2/3/4 Rule
Unclear underwriting standards can result in rejected credit applications and wasted hard credit inquiries. Understanding a bank’s internal rules before applying protects your credit score.
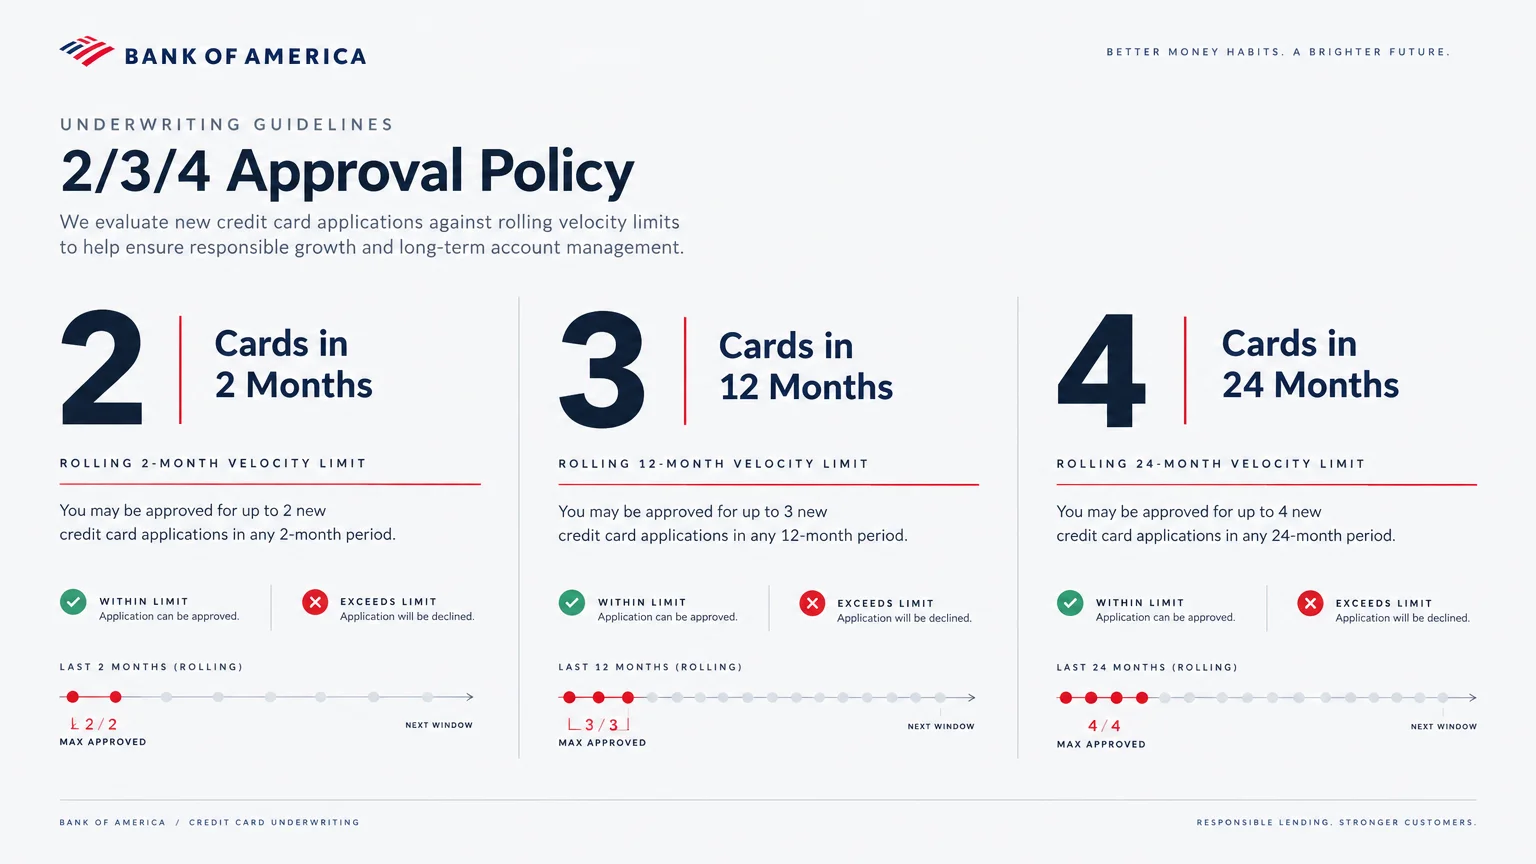
Bank of America operates under a well-documented underwriting standard colloquially called the “2/3/4 Rule.” This internal guideline limits how many Bank of America cards you can open across specific time windows.
Under these parameters, you can receive approval for a maximum of two cards across a rolling 2-month window. You are limited to three cards within 12 months, and four cards within 24 months.
Because these guidelines are consistent, you can structure your credit applications strategically. You can verify your standing before submitting an application, avoiding unnecessary hard pulls on your credit report.
You can monitor your recent inquiries and account openings through AnnualCreditReport.com before applying. Reviewing your files ensures you remain comfortably within Bank of America’s velocity thresholds.
Don’t Make These Mistakes
While the Bank of America Unlimited Cash Rewards card delivers tremendous utility, minor mistakes can eliminate your earnings. Avoiding key operational pitfalls protects your financial progress.
- Carrying a Revolving Balance: Accumulating unpaid balances triggers regular variable interest between 17.74% and 27.74%. A single month of double-digit interest charges wipes out an entire year of 1.5% cash back.
- Using the Card Overseas: The card imposes a 3% foreign transaction fee on all purchases made outside the United States. Using this card internationally results in a net 1.5% loss on every transaction.
- Missing the 60-Day Transfer Window: The introductory 3% balance transfer fee applies only to transfers requested within the first 60 days. Waiting until day 61 increases your transaction fee to 5%.
- Defaulting on Payment Deadlines: Missing a monthly due date can trigger a penalty APR reaching up to 29.99%. That punitive interest rate can remain attached to new purchases indefinitely.
Always configure automatic payments for the full statement balance each month. Automating your payments ensures you never forfeit rewards to avoidable late penalties or interest charges.
When Professional Advice Is Worth It
Credit card cash back offers an effective optimization tool for disciplined household budgets. However, credit cards cannot fix underlying structural debt problems or severe cash flow shortages.
If you carry substantial five-figure credit card debt across multiple lenders, a 1.5% rewards card is not your solution. You should consult a non-profit credit counselor accredited through the National Foundation for Credit Counseling (NFCC).
Similarly, moving substantial assets to qualify for BofA Rewards Preferred Honors tiers involves major tax and asset allocation questions. A fee-only financial planner or certified public accountant (CPA) can help you weigh those decisions objectively.
Never move retirement savings or diversified investments simply to chase credit card multipliers. Professional financial planners ensure your overarching investment strategy dictates your banking choices—not the other way around.
Frequently Asked Questions
Do my Bank of America cash back rewards expire?
No, your cash back rewards do not expire as long as your account remains open and in good standing. If you close your credit card account voluntarily, you forfeit any unredeemed rewards balances.
How does the 2026 BofA Rewards overhaul affect existing cardholders?
The May 2026 update replaced the Preferred Rewards structure with BofA Rewards™. Existing cardholders can now access rewards boosts starting with a $0 balance in their checking account, though higher tiers require combined deposit balances.
Can I convert an existing Bank of America card to this product?
Yes, Bank of America frequently allows existing cardholders to execute a product change to the Unlimited Cash Rewards card. Contact customer service to verify your account’s eligibility for an internal product transfer without a hard inquiry.
Does this card charge a foreign transaction fee?
Yes, this card charges a 3% foreign transaction fee on all transactions processed in foreign currencies or outside the United States. You should carry a dedicated travel card with zero foreign transaction fees when traveling abroad.
Next Steps for Your Household Strategy
The Bank of America Unlimited Cash Rewards card stands out as one of the most dependable cash back products available. Its $0 annual fee and flat 1.5% base return provide reliable value without administrative friction.
If you maintain checking or investment balances with Bank of America and Merrill, the card becomes even more attractive. Review your current banking relationships today to determine which BofA Rewards tier you qualify for before applying.
Financial outcomes vary based on individual income, credit history, and circumstances. This article provides general guidance only. Consult a qualified financial planner, CPA, or consumer attorney for advice specific to your situation.
Last updated: October 2026. Rates, benefit amounts, and tax rules change—always verify current details at official sources.